
A gift, benefit or personal connection can affect a purchasing decision or create a concern about its impartiality. Disclose the relevant facts through the organisation’s process before accepting an offer or participating in a decision that may be affected.
Do not assume a low-value offer is automatically permitted, that every organisation has the same threshold or that disclosure alone authorises acceptance. The actual policy and applicable requirements need to be checked.
Identify the offer or interest clearly
Describe what was offered, by whom, its connection to the purchasing process and whether any relevant decision is pending. For a personal connection, explain the relationship and its relevance rather than simply saying you can remain objective.
Queensland’s Crime and Corruption Commission publishes gifts and benefits guidance and procurement integrity guidance for public-sector contexts. Other organisations must check their own framework rather than treating a public-sector rule as a universal private-business policy.
Where requirements are uncertain, ask the responsible integrity, procurement or legal contact before proceeding.
Use a practical disclosure record
Provide:
- Context: the procurement or supplier relationship involved.
- Offer or connection: factual details needed for assessment.
- Timing: when it became known and decisions still pending.
- Participation: work or supplier contact already undertaken.
- Policy: relevant requirement and authority to determine the response.
- Decision: acceptance, refusal or participation arrangement actually authorised.
- Action: return, register entry, restricted involvement or other required step.
- Review: changed circumstances needing another declaration.
Keep personal and commercial information in the approved restricted process. A broad team message is not necessarily the right way to disclose sensitive details.
A fictional supplier invitation
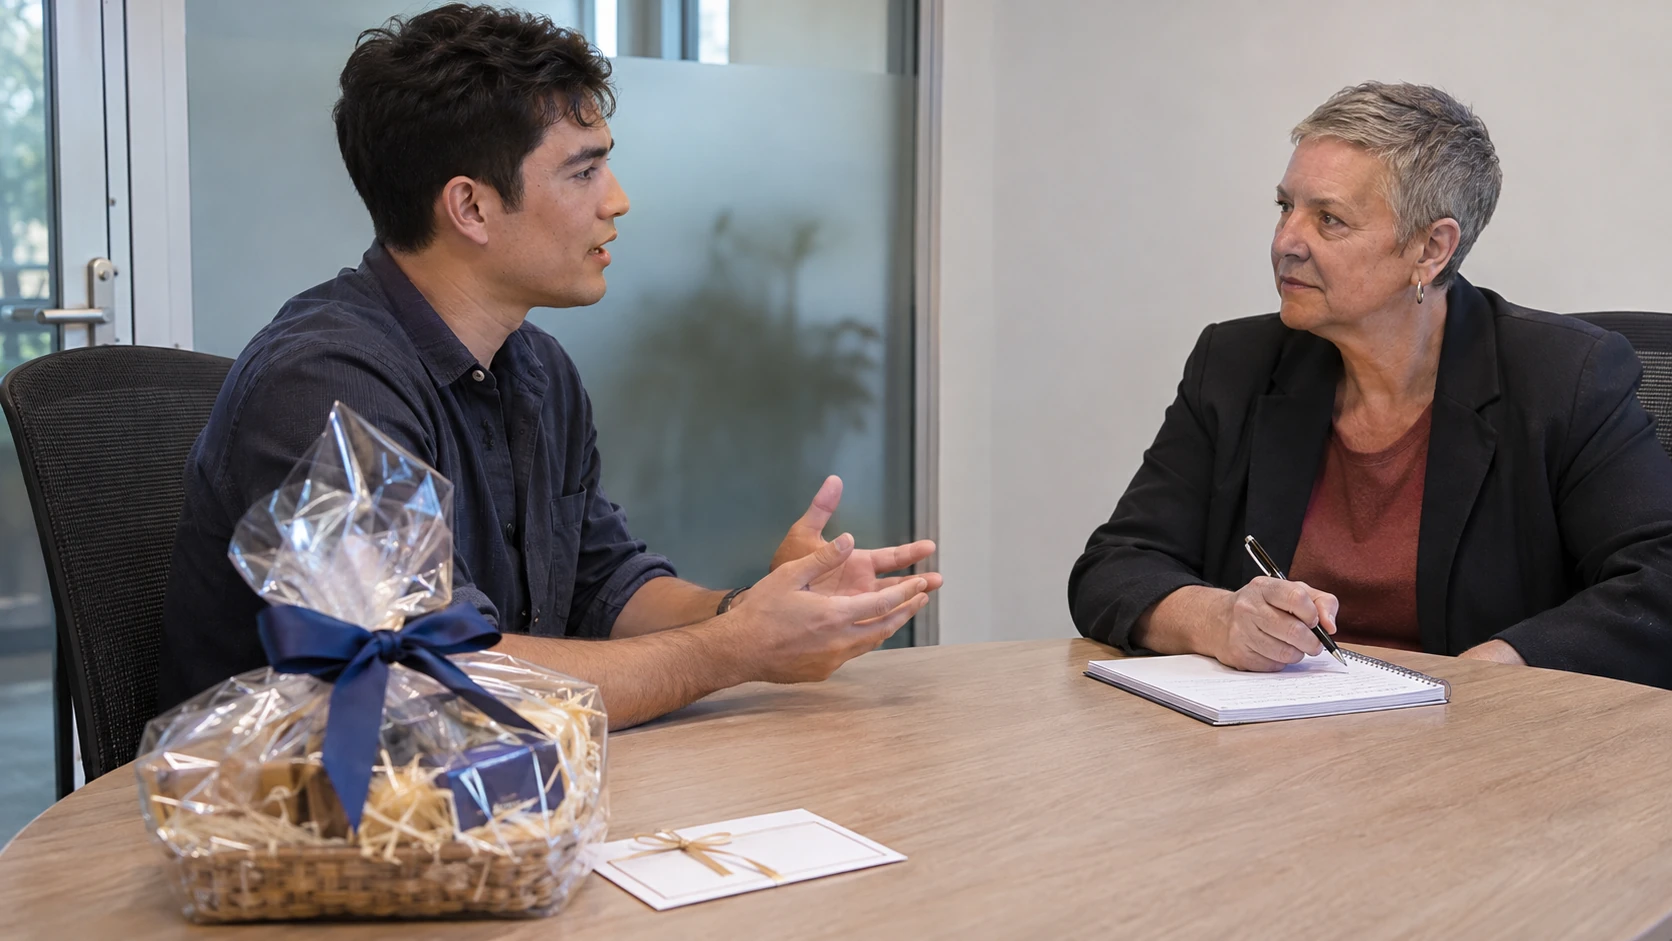
In this invented example, an employee evaluating quotes receives an invitation from one supplier to a hospitality activity. Before responding, they disclose the invitation and their current role in the purchasing process.
The authorised reviewer considers the applicable policy and records the decision and actions required. The employee follows that direction and checks whether any procurement participation needs to change.
The example does not suggest the invitation is acceptable because its estimated value is below an invented amount, or that recording it in a spreadsheet automatically resolves the issue.
Implement the management arrangement
If participation is restricted, ensure meeting invitations, document access and assessment discussions reflect the decision. Do not continue influencing the outcome informally after being removed from a formal approval step.
If an offer is refused or returned, record the action through the actual process. Where conduct raises a concern requiring reporting or investigation, use the designated pathway rather than attempting to settle it privately.
Revisit the declaration when circumstances change
Update relevant disclosures if the relationship, offer or purchasing responsibility changes. Retain the decision evidence and follow any review requirements.
A useful disclosure leads to a clear, implemented response based on the actual policy. Its purpose is an accountable purchasing process, with enough evidence to understand how a potential influence was identified and managed.